Working Capital CC / OD
Support your day-to-day business operations with flexible working capital finance for cash-flow gaps, regular expenses and short-term funding needs.
What Is Working Capital Finance?
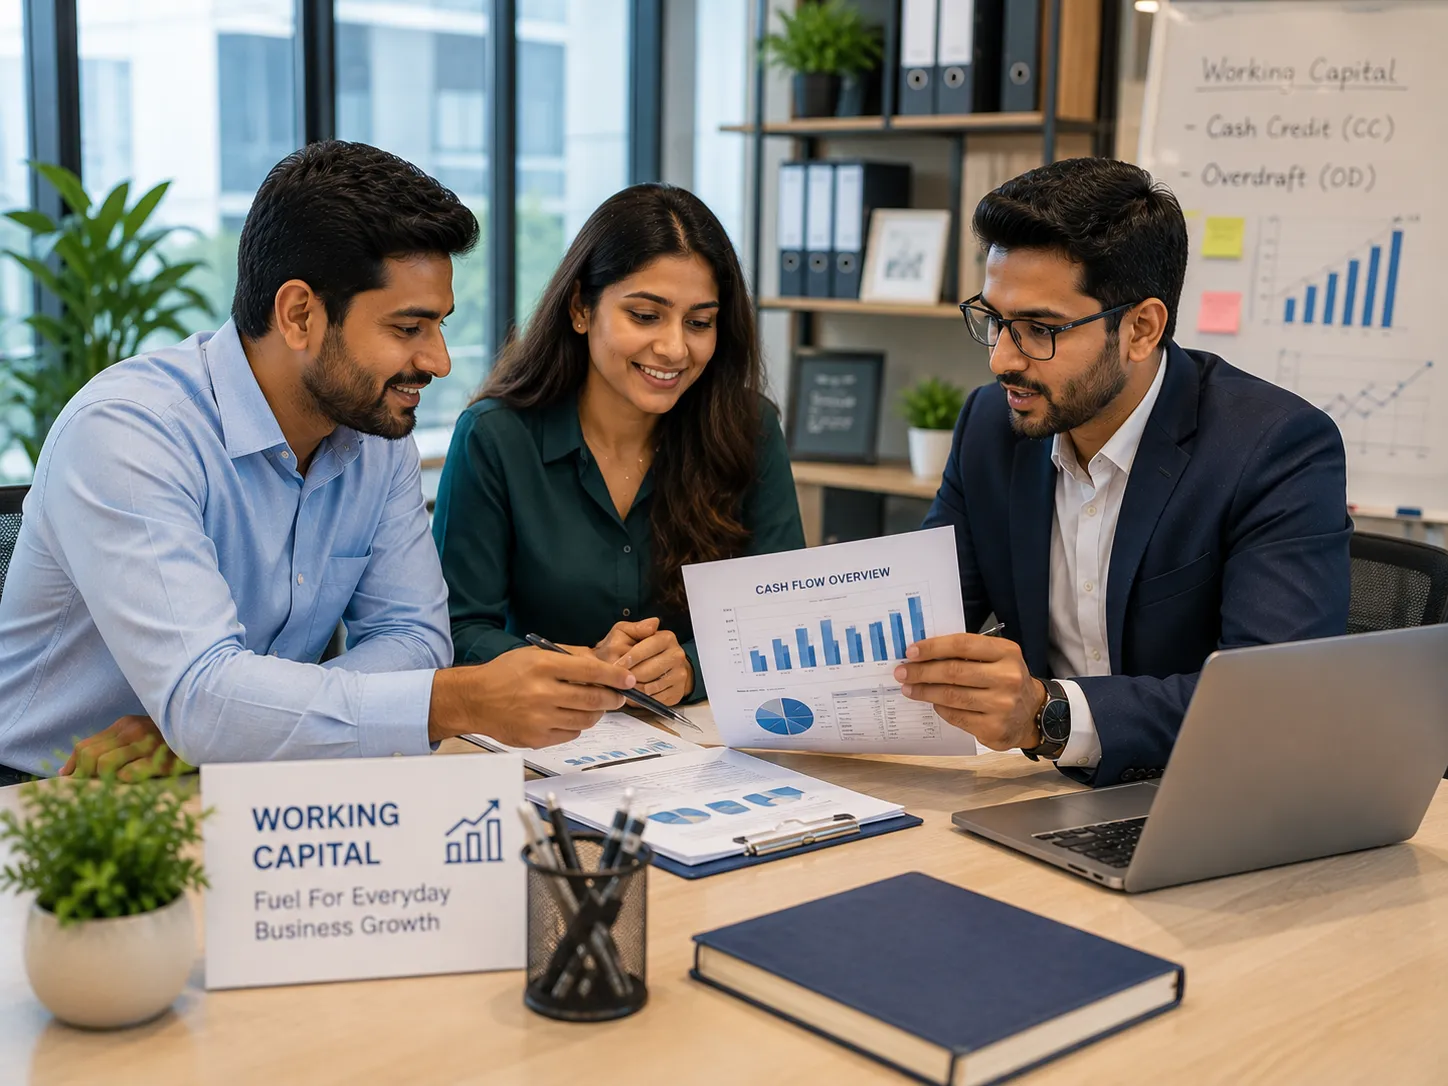
Working capital finance helps businesses manage short-term funding needs that arise while running regular operations. Cash Credit (CC) and Overdraft (OD) facilities can provide access to funds within an approved limit, subject to applicable lender terms.
Manage Regular Expenses
Support eligible day-to-day operating expenses when business cash flow needs additional flexibility.
Bridge Cash-Flow Gaps
Manage timing differences between business receivables and recurring payment obligations.
Support Business Operations
Use working capital for eligible inventory, supplier, payroll or other operational requirements.
CC and OD limits, usage conditions and applicable charges can vary according to the business profile and lender assessment.
Keep Your Business Cycle Moving Without Cash-Flow Gaps
Business payments often need to be made before customer receivables arrive. Working capital finance can help eligible businesses manage this timing gap and maintain continuity across the operating cycle.
Purchase Stock
Arrange eligible funds for inventory, raw material or regular procurement requirements.
Run Operations
Support eligible payroll, supplier payments and other recurring operating expenses.
Complete Sales
Continue serving orders and business demand while payments may still be outstanding.
Receive Payments
Customer receivables restore liquidity and help complete the operating cash-flow cycle.
CC / OD facilities can provide eligible businesses with access to funds within an approved limit while they wait for receivables, subject to lender assessment and applicable terms.
What Lenders May Review For CC / OD Approval
Working capital limits are generally assessed on the strength of the business, its operating cycle and repayment ability rather than on a single factor.
Business Turnover
Revenue size and business activity may help determine the scale of the working capital requirement.
Banking Conduct
Account behaviour, transaction flow and existing banking relationships may form part of the assessment.
Financial Records
Financial statements, tax records and related information may be reviewed to understand business performance.
Operating Cycle
Inventory movement, receivable period and supplier payment cycle can influence the working capital assessment.
Nature and continuity of regular business operations.
Consistency of inflows, outflows and operating liquidity.
Ability to manage existing and proposed financial obligations.
Required limit and intended working capital purpose.
Exact eligibility, limit, pricing, security requirements and terms depend on lender assessment and applicable policies.
Documents Commonly Required for CC / OD
Keeping your business and financial records organised can make the application review smoother. Exact documentation may vary according to the lender, business constitution and facility requested.
Basic Business Documentation
Documents that help establish the identity, constitution and legal existence of the business.
Business Financial Information
Financial information can help lenders understand turnover, profitability, liabilities and repayment capacity.
Bank Account & Conduct
Banking records may be reviewed to understand transaction behaviour and the operating cash flow of the business.
Working Capital Requirement
Lenders may also seek information about the requested facility and the business requirement it is intended to support.
This is an indicative checklist. The final document list depends on the lender, applicant profile, business type and proposed facility.
STAGES FROM REQUIREMENT
TO FACILITY SETUP
A Clear Route to Your Working Capital Facility
The CC / OD process begins with understanding your actual business requirement and moves through documentation, lender review and final facility setup.
Understand the Requirement
Review the operating cash-flow gap, purpose of funds and the approximate working capital requirement of the business.
Build the Application File
Organise relevant KYC, business registration, banking, tax and financial documents for the proposed facility.
Move the Case to the Lender
Submit the application with supporting information so the lender can begin its formal credit review.
Credit Assessment
Business performance, banking conduct, repayment capacity and applicable security requirements may be evaluated.
Sanction & Facility Setup
If approved, the lender communicates the sanctioned limit and applicable terms before completing facility formalities.
Every application is assessed individually. Eligibility, sanctioned limit, pricing, security and turnaround time vary according to business profile, documentation and lender policy.
Common Questions About Working Capital (CC / OD)
Understand the basics before you apply. These answers cover common questions about Cash Credit, Overdraft, eligibility, documentation, usage, limits and lender assessment.